
Headlines about McDonald’s store closures and restructuring charges have been circulating for a while. It’s enough to make customers, employees, and investors wonder whether something serious is going on behind the scenes.
The short answer is no — McDonald’s is not going out of business. But let’s look at the actual numbers rather than just saying that and moving on.
McDonald’s Financial Position as of 2024–2025
If you want to know whether a company is in trouble, start with the income statement. McDonald’s full-year 2024 consolidated revenues came in at approximately $25.9 billion, up 2% compared to the prior year. Systemwide sales — which include all franchise locations — exceeded $130 billion globally.
Operating margin held near 45%, which is exceptionally strong for any business. Diluted earnings per share came in at $11.39, a modest 1% decline from the year before. Net income remained above $8 billion, consistent with prior years.
These are not the numbers of a company heading toward closure. They reflect a business that is highly profitable and generating significant cash, even while navigating a period of slower growth.
What the Store Closures and Restructuring Program Actually Mean
McDonald’s has been running a restructuring initiative called “Accelerating the Organization.” In 2024, that program recorded approximately $221 million in pre-tax restructuring charges. Those charges weighed on earnings in the second and third quarters, which is partly why some quarterly results looked softer than usual.
But restructuring charges are not the same as a company falling apart. They reflect deliberate decisions to streamline operations, reduce overhead, and position the business for better efficiency going forward. Think of it like a homeowner paying for major renovations — the cost hurts in the short term, but the goal is a better-functioning structure afterward.
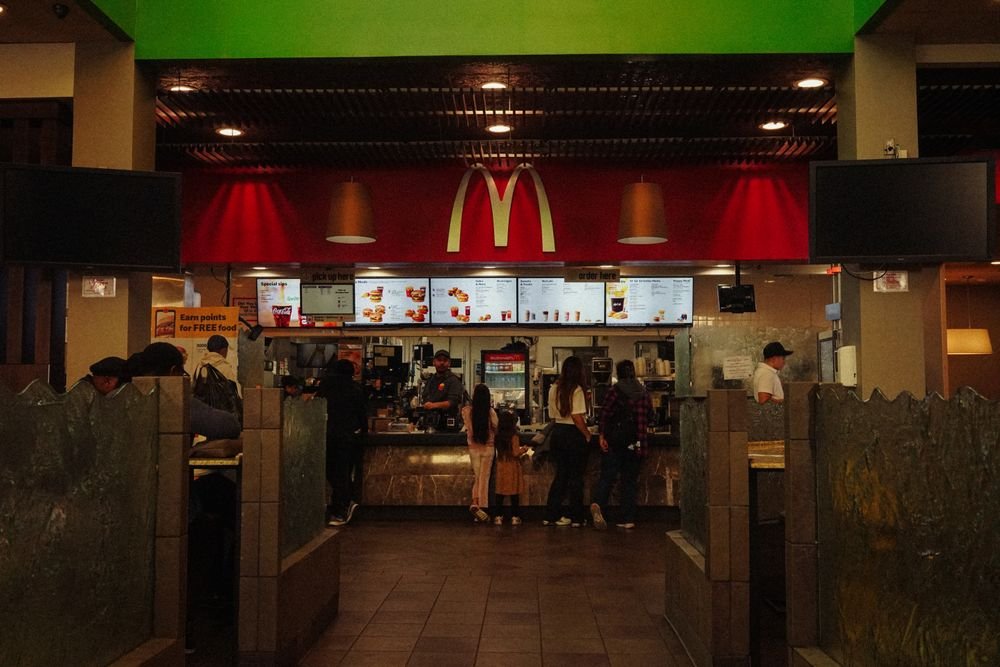
Here is the detail that often gets left out of the negative headlines: McDonald’s opened over 2,100 new restaurants across its system in 2024. That is net unit growth, not contraction. Closing a handful of underperforming locations while opening more than 2,100 new ones is portfolio management — it is not a company in retreat.
Local Closures Are Not the Same as Global Failure
When two or three McDonald’s locations close in your city, it can feel significant. But those closures are often driven by local factors: lease costs, low foot traffic, or a nearby location that performs better.
At the same time, McDonald’s may be opening dozens of new restaurants in other markets — including high-growth regions in Asia and the Middle East. Local anecdotes and global systemwide metrics tell very different stories.
Where McDonald’s Is Seeing Real Pressure
This article would not be balanced without acknowledging where the business has genuinely softened. Global comparable sales — which measure performance at existing locations — declined 0.1% for full-year 2024. That is essentially flat, but it does represent a shift from the stronger growth McDonald’s posted in prior years.
International segments showed modest same-store sales declines, tied to macroeconomic pressure and shifts in how consumers are spending. Inflation has made diners more price-conscious, and that affects even a brand with McDonald’s scale.
In Q2 and Q3 2024, net income dropped roughly 12% year over year. However, that decline was largely attributed to the restructuring and impairment charges mentioned above — not a fundamental collapse in customer demand.
Competitive pressure from other fast-food chains is also real. Value-focused rivals have been aggressive, and McDonald’s has had to respond with its own value promotions. None of this is unusual for a mature consumer brand operating in a competitive market. McDonald’s still holds its position as the largest fast-food brand in the world by sales.
Why Rumors About McDonald’s Closing Keep Circulating
It helps to understand where these stories come from, because they do not appear out of nowhere.
In 2015, a survey of McDonald’s franchisees described the company as being in a “deep depression” and facing its “final days.” That language was widely picked up by media outlets. What it actually reflected was franchisee frustration over operational challenges and margin pressure at the time — not a formal financial forecast. McDonald’s subsequently recovered, modernized, and grew. That quote was a snapshot of dissatisfaction, not a prediction that came true.
On social media, Reddit threads occasionally feature posts theorizing that McDonald’s could be “nearly dead in 50–75 years” due to health trends and shifting consumer behavior. Those are personal opinions. They are not expert analysis, and they describe speculative long-term scenarios rather than any current financial reality.
There is also the matter of legal language. McDonald’s SEC filings and proxy statements include references to hypothetical scenarios such as liquidation, dissolution, or business combinations. This is standard corporate governance language that appears in virtually every public company’s filings. It exists to outline shareholder rights in various theoretical situations — it is not a signal that management is planning to shut down.
Finally, media coverage of closures at other fast-food chains — such as Arby’s — can create a general impression that the entire fast-food industry is struggling. That framing does not apply equally to every brand, and it certainly does not reflect McDonald’s current financial position.
What McDonald’s Dividend and Expansion Plans Signal to Investors
Investors who want to assess a company’s health pay close attention to dividends. Companies that expect financial difficulty typically cut or suspend dividends to preserve cash. McDonald’s did the opposite.
In late 2024, McDonald’s raised its quarterly dividend by 6% to $1.77 per share. A company raising its dividend is communicating confidence in its future cash flows. It does not eliminate all risk, but it is a meaningful indicator of financial stability.
Looking ahead, McDonald’s 2025 investor materials indicate that net restaurant unit expansion is expected to contribute slightly over 2% to systemwide sales growth. That is a growth plan, not an exit strategy.
For anyone trying to understand what genuine financial distress looks like, consider the contrast. A company approaching failure typically shows sharp revenue declines, sustained net losses, dividend cuts, a shrinking store count, and warning signs in SEC filings about its ability to continue operating. None of those patterns are present in McDonald’s current data.
If you follow business news regularly and want a reliable source for cutting through this kind of noise, The Business Layer covers financial and corporate topics with a focus on clarity and accuracy.
How to Evaluate These Claims for Yourself
Whether the subject is McDonald’s or any other large company, a few indicators are worth watching if you want to assess genuine risk:
- Revenue trend: Is total revenue growing, flat, or falling consistently?
- Net income: Is the company profitable after accounting for all costs?
- Dividend behavior: Is the dividend being raised, held steady, or cut?
- Net restaurant or unit count: Is the company opening more locations than it closes?
- Debt and liquidity: Does the company have access to capital, or is it burning through cash?
- Formal filings: Has the company filed for bankruptcy protection or issued going-concern warnings?
Applying those questions to McDonald’s current data produces a consistent answer. Revenue is up. Net income is in the billions. The dividend is rising. More restaurants are opening than closing. No bankruptcy filing exists. No going-concern language has appeared in its audit reports.
The Bottom Line
McDonald’s is not going out of business. The company is managing a period of slower growth, working through a restructuring program, and adjusting to competitive and macroeconomic pressure. Those are normal challenges for a global business of its size.
The gap between the headlines and the financial data is significant. Store closures, restructuring charges, and flat comparable sales are worth monitoring — but they look very different from actual corporate distress when you examine them in context.
If you are a customer, employee, franchisee, or investor trying to form a clear picture, the data is publicly available and worth reading. The 2024 Form 10-K, the quarterly earnings releases, and the investor overview deck all tell a straightforward story: a profitable, expanding company navigating a moderately challenging environment, not one approaching its end.
Read Also:
